
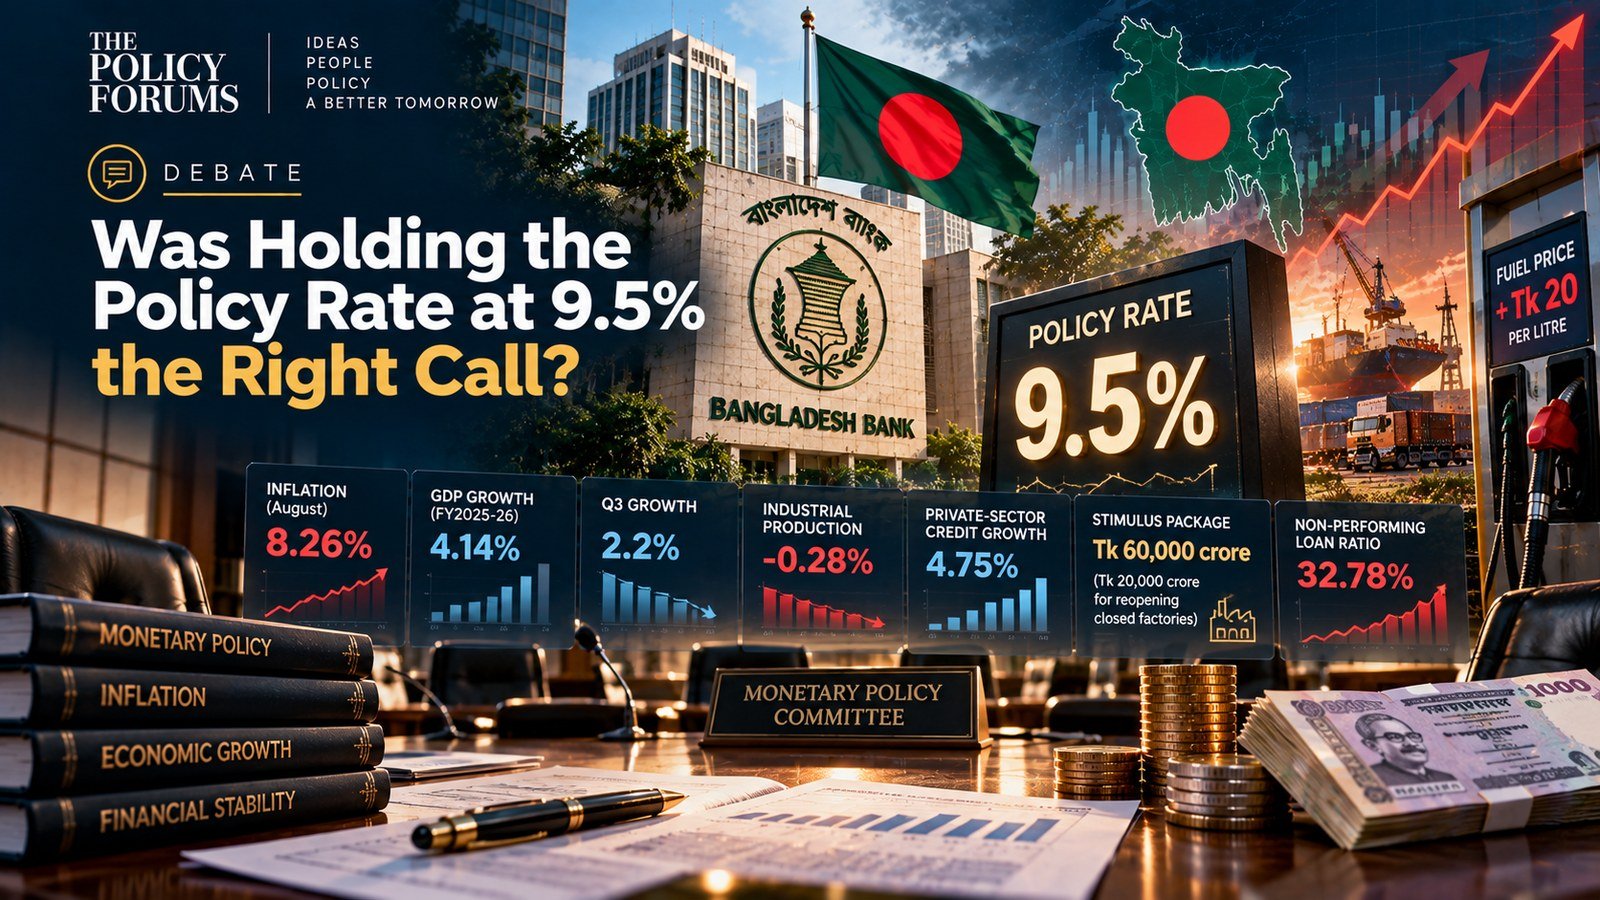
The trigger: Bangladesh Bank’s first-ever quarterly monetary policy, announced September 30, held the policy rate unchanged at 9.5% even as headline inflation sat at 8.26% in August and GDP growth slowed to an estimated 4.14% for FY2025-26, with a third-quarter print of just 2.2%.
The case for holding: With industrial production contracting 0.28% and private-sector credit growth already down to 4.75%, further tightening risked deepening the slowdown. The central bank’s own Tk60,000 crore stimulus package — including Tk20,000 crore for reopening closed factories — signals it judged growth, not inflation, as the more urgent risk.
The case for tightening: Inflation at 8.26% remains far above any reasonable target, and the central bank itself acknowledged that September’s Tk20-per-litre fuel price hike “is likely to raise transport and production costs” — an admission that more inflationary pressure is already in the pipeline. Holding rates while flagging a known upside inflation risk looks, to critics, like accepting higher prices now in exchange for growth support that a 4.75% credit growth rate suggests isn’t reaching the real economy anyway.
Policy implication: A non-performing loan ratio of 32.78% complicates both sides of the argument — tightening further could push more borrowers into distress, but holding rates does little to fix a banking sector whose core problem looks more structural than cyclical.
Where I land: The decision to hold is defensible given the growth data, but pairing it with an explicit acknowledgment of fresh fuel-driven inflation risk, without a clearer plan to address it, leaves the central bank exposed if the next quarterly review shows inflation accelerating rather than easing.
Confidence level: Moderate. The inflation and growth figures are official central bank data, but assessing whether the rate decision was “right” depends on inflation and credit trends that will only be clear in the next quarterly cycle.
Related reading: BB announces monetary policy for Q2 of FY27 — The Business Standard